You don't need another guru. You need the law on your side.
You've watched the videos. Joined the groups. Copied the templates. And you're still stuck the
moment a bureau stalls, reinserts, or denies. Kaironeek University is where that stops — real statutes, real
case law, and a mentor who shows you exactly how to use them.
That's why Kaironeek University exists. To solve that exact problem.
Why We Built This
Credit repair education has a depth problem.
01
Shallow answers, everywhere
Facebook groups, YouTube, and search results recycle the same surface-level talking points — and often
get the law wrong.
02
Knowledge gaps lead to risk
Without real legal grounding, some practitioners drift into practices that put their business and their
clients at risk.
03
Sold on marketing, not mastery
Most programs teach you how to sell credit repair. Few teach you how to actually deliver the results
you're selling.
04
Stuck on factual disputing
Template-based factual disputing is where most training stops. It's a floor, not a ceiling — and it's not
where results come from.
That's not your fault. The truth is, most programs only teach tactics not understanding.
At Kaironeek University, we teach you how to think. We teach you the system. We show you what the law really says, why it matters, and how to use it with power.
The Kaironeek Method
We teach the system behind the law — not just the letter template.
I
Historical Analysis
Understand the abuses that led to FCRA, FDCPA, TILA, and ECOA — and why that history still shapes how
they're enforced.
II
Legal Interpretation
Read the regulations and case law that actually govern how bureaus, creditors, and collectors are required
to act.
III
Practical Application
Apply it: build custom disputes, sequence your strategy, and respond to stalls and denials with real
authority.
Who This Is For
Built for two kinds of students.
Credit repair business owners
Especially those just starting out or stuck — you'll learn to run a compliant business and deliver results
your clients can see.
Consumers taking control
Learn your rights under consumer law well enough to fix your own credit and never be intimidated by a
creditor or collector again.
Your Membership
Everything you get as a student.
1
Live classes, every week
2–3 hours of live instruction each Monday evening at 8 PM — real teaching, not a recording.
2
1:1 mentorship calls
Book time with Richard directly when you need help working through a dispute or a business decision.
3
Skool community access
Your daily home base for lessons, discussion, and classmates — hosted on Skool. ● Skool
4
Private WhatsApp group
Stay connected with fellow students every day so your learning never stalls between classes.
5
Group mentorship calls
Occasional group sessions to work through common questions and real case scenarios together.
6
Book access, for a limited time
Incremental access to Richard's Consumer Law Credit Repair Series as you progress through the program.
Enrollment
Four steps to get started.
1
Create your account
Set up your student login — this is your home base for classes, mentorship, and community.
2
Sign your contract
Review and sign your enrollment agreement directly on the site.
3
Pick your payment plan
Choose from five tuition options — pay in full or start with a smaller down payment.
4
Submit your payment
Complete checkout and you're in — live classes, mentorship, and community await.
Tuition is a one-time enrollment cost, plus a modest monthly subscription that begins after your first
month for ongoing access to live classes, mentorship, and community.
No. The program is built for laypeople — you're guided from the fundamentals through advanced
application, step by step.
Yes — the curriculum is built with credit repair business owners specifically in mind, alongside
consumers learning to fix their own credit.
Every Monday evening at 8 PM, with a dedicated mentorship hour available separately to work through your
own disputes.
Founder of Kaironeek University and Kaironeek Financial — dedicated to equipping everyday people
with the knowledge and tools to navigate the complex world of credit and consumer law.
Layman ScholarNot a lawyer, by design
Classics & PhilosophyAcademic background
Sabbath ObserverFaith-guided practice
Academic & Intellectual Background
A foundation built on history, not just statutes.
Beyond his expertise in consumer law, Richard
holds college degrees in classics and philosophy — disciplines that shaped his analytical thinking and his deep
appreciation for the intellectual traditions behind modern law and society.
That background is why Kaironeek University doesn't stop at "here's
the template." Richard teaches the historical circumstances that gave rise to consumer protection law, the legal
traditions that shape how it's applied today, and the regulations and case law that govern how it plays out in
practice.
Faith & Values
Commitment to Faith and Values
Richard is deeply committed to his Christian faith, and his values
guide both his professional and personal life. As a devoted Sabbath observer, he places great importance on
faith, family, and the pursuit of truth. His approach to consumer law isn't merely academic — it's rooted in a
historical and ethical framework that seeks justice for consumers who have been wronged by creditors, debt
collectors, and credit bureaus.
A Unique Approach to Learning
Layman's scholarship, taken seriously.
With a reputation for rigorous research and a
commitment to layman's scholarship, Richard stands apart in the non-lawyer consumer law space. He believes real
knowledge takes time, and that understanding consumer rights requires studying the historical circumstances
under which consumer laws were enacted.
His work extends beyond theory — Richard is actively engaged in the
practical application of consumer law, using case law, historical analysis, and regulatory interpretation to
challenge unfair credit practices. Through Kaironeek University, he's built a space where credit repair
professionals and consumers alike can gain a deeper, historically grounded understanding of their rights.
Learn directly from Richard.
Weekly live classes, 1:1 mentorship, and a community built around real legal mastery — not another round of
templates.
Not tactics. Not templates. A real, structured course of study in the statutes, regulations, and
case law behind credit reporting and debt collection — the same material a legal researcher would study, taught
for laypeople.
16Core subjects
2Certification tracks
WeeklyLive instruction
The Full Course of Study
Sixteen subjects, taught in sequence.
01
Your Right to Privacy — Its History and Application in Consumer Law
Study the legal development of privacy in the United States and how it protects your credit file, financial data, and personal identity. Focus: We examine how privacy law intersects with credit reporting and consumer rights.
02
The History of Credit Reporting and Modern Credit Bureaus
Trace how consumer reporting evolved from merchant notes to modern credit bureaus and understand the structure and power of agencies like Experian, Equifax, and TransUnion. Focus: We study historical abuses and the legal shifts that gave rise to the modern credit system.
03
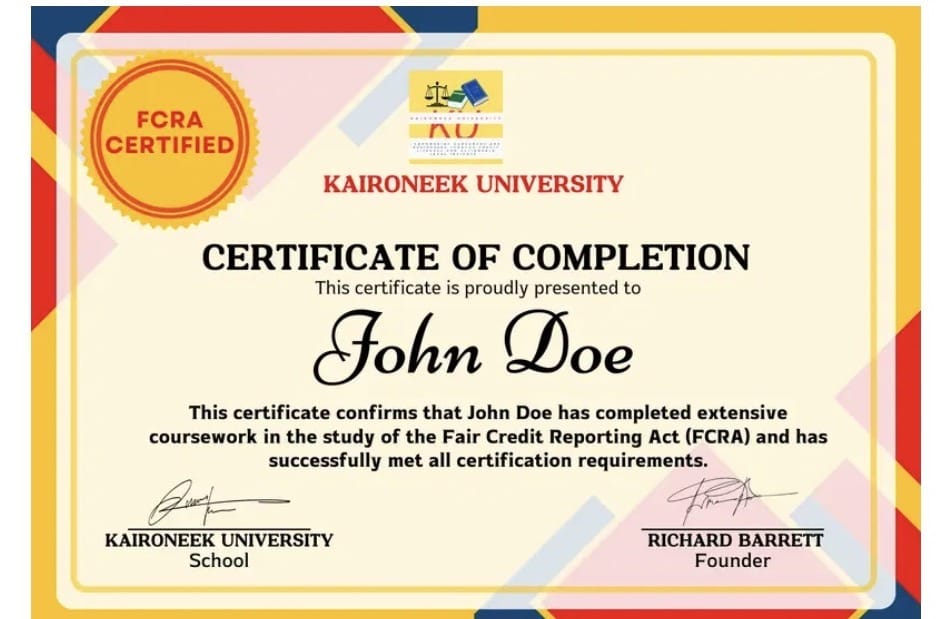
Fair Credit Reporting Act (FCRA) Certification
Learn the complete federal law that governs credit reports. Understand permissible purpose, dispute rights, furnisher duties, legal remedies, and case law enforcement. Coverage: Full certification course.
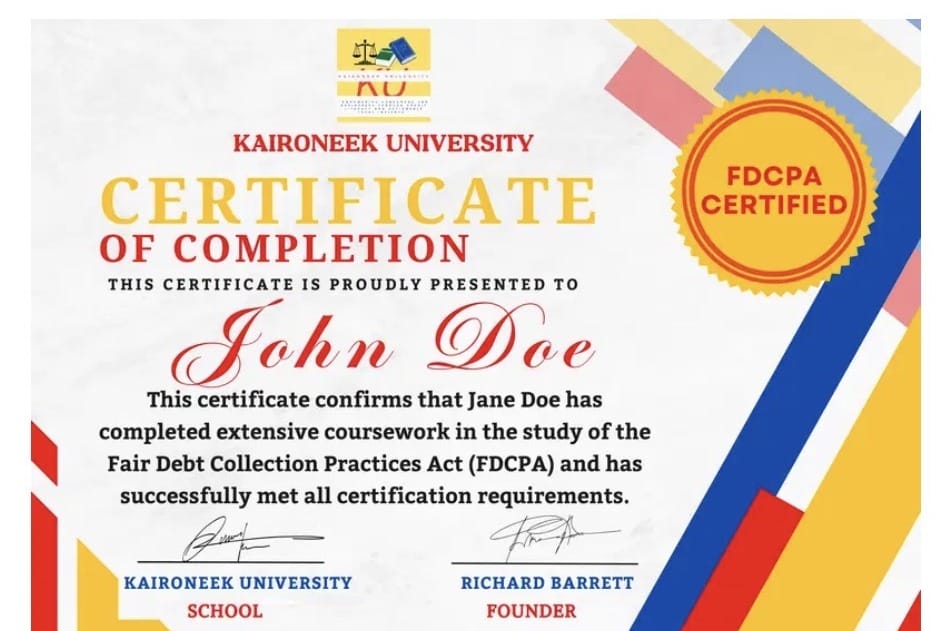
Master the law that governs debt collectors, including illegal practices, required notices, validation rules, and your enforcement rights. Coverage: Full certification course, including Regulation F and court interpretation.
05
Truth in Lending Act (TILA)
Learn how lenders must disclose credit terms, interest rates, finance charges, and cancellation rights. Focus: We highlight provisions most useful in credit repair, defense, and litigation.
06
Equal Credit Opportunity Act (ECOA)
Understand how the law prohibits credit discrimination based on race, gender, age, marital status, and more. Focus: We cover how ECOA governs underwriting, adverse action, and credit denial.
07
Fair Credit Billing Act (FCBA)
Learn how to dispute billing errors, unauthorized charges, and unfair credit card practices. Focus: Billing error resolution procedures and consumer protections.
08
E-Sign Act
Understand how electronic signatures and digital agreements are treated under federal law especially in credit and debt-related contracts. Focus: The legal validity and implications of e-signed documents in consumer transactions.
09
Foundations of Contract Law
Study how contracts are formed, enforced, and challenged. Learn about offer, acceptance, consideration, breach, and remedies especially in the context of credit agreements. Coverage: Full foundational course in contract law.
10
Tort Laws Relevant to Credit
Explore civil wrongs like defamation, invasion of privacy, and negligent reporting, and how they form the basis of lawsuits against credit bureaus and debt collectors. Focus: We cover torts that apply to consumer protection and credit reporting.
11
Credit Score Fundamentals
Understand what makes up your credit score, how FICO and VantageScore work, and how to strategically build and protect your credit. Coverage: Full breakdown of score components, models, and usage.
12
Credit Repair Organizations Act (CROA)
Learn the federal law that governs how credit repair companies must operate, including required disclosures, service limitations, and consumer protections. Coverage: Full compliance training for professionals.
13
Credit Repair Disputing
Master the process of reading credit reports, identifying errors and violations, and writing legal-based disputes to bureaus, furnishers, and collectors. Coverage: Full practical course with legal strategy, dispute formats, and regulatory compliance.
14
Debt Collection Defense
Learn how to defeat debt collectors using licensing laws, assignment flaws, state regulations, and federal statutes. Coverage: Full legal training in non-courtroom debt defense strategy.
15
Debt Collection Litigation
Prepare for legal action by learning how to answer complaints, assert defenses, challenge standing, and pursue counterclaims under federal and state law. Focus: Litigation training specific to defending debt-related lawsuits.
16
Arbitration — How It Works and Its Role in Consumer Law
Understand what arbitration is, how it differs from court, when to invoke it, and how it's used in debt collection and credit-related disputes. Focus: Consumer strategy in mandatory arbitration settings.
17
Fundamentals of Marketing (Inductive Reading-Based Course)
Instead of surface-level marketing tricks, this course immerses students in the foundational ideas of persuasion, brand building, and communication studying classic texts alongside contemporary strategies. Coverage: Full course grounded in close reading of timeless works and real-world application.
18
Foundations of Sales (Inductive Reading-Based Course)
This course teaches ethical, powerful sales by studying masterworks in sales literature analyzing why they work, how humans make decisions, and how to sell without manipulation. Coverage: Full inductive training from classic books, psychological studies, and sales case analysis.
The Kaironeek Method
Three layers to real mastery.
I
Historical Analysis
Understand the abuses that led to FCRA, FDCPA, TILA, and ECOA — and why that history still shapes how
they're enforced.
II
Legal Interpretation
Read the regulations and case law that actually govern how bureaus, creditors, and collectors are required
to act.
III
Practical Application
Apply it: build custom disputes, sequence your strategy, and respond to stalls and denials with real
authority.
Certifications
Two certifications built into the program.
FCRA Certification
Master the laws governing credit reporting and consumer rights.
FDCPA Certification
Learn how to identify and challenge unfair debt collection practices.
Legal education should unlock doors, not close them.
Access to financial and legal knowledge shouldn't be limited to those who can pay thousands
upfront. Five flexible payment options, no credit check, so you can start mastering the law today.
Choose Your Plan
Five ways to enroll. No credit check.
Best Value
Option 1
$2,579
One-time payment · includes tuition + first month's $79 subscription
* Figures shown are current tuition figures — confirm
against your live Stripe pricing before this page goes live.
Every Plan Includes
What you get, no matter which plan you choose.
1
Live classes, every week
2–3 hours of live instruction each Monday at 8 PM.
2
1:1 mentorship calls
Direct access to Richard when you need help.
3
Skool community access
Your daily home base for lessons and classmates.
4
Private WhatsApp group
Daily connection with fellow students.
5
Group mentorship calls
Work through real case scenarios together.
6
Book access, for a limited time
Incremental access to the Consumer Law Credit Repair Series.
Why so many options?
Because we know the struggle. Most students have been misinformed, overcharged, or trapped in a cycle of bad
credit and bad advice. Price shouldn't be what keeps you from real knowledge.
Every review here comes from an active Kaironeek University student — pulled directly from our
community and mentorship channels, with identifying details removed to protect their privacy.
1:1 + GroupMentorship access
WeeklyLive class attendance
Pro SeWins against major creditors
Watch
Students, in their own words.
Video
Business OwnerOn finally understanding consumer law well enough to
teach it
Video
Career ChangerOn going from confused beginner to confident dispute
writer
Video
Consumer StudentOn fixing her own credit after years of stalled
disputes
Video
Credit Repair OwnerOn the mentorship call that changed how he runs his
business
Read
What students are saying.
“
This is the best credit university in the entire world. I have learned things I didn't learn in 23 years of
experience.
Student, Facebook Community
“
Thank you for all the hard work you have done to help us understand the real deal about consumer law. I
really appreciate this education — I've learned so much in just the short time I've been part of the class.
Mentee, Live Class Chat
“
I have finally found the integrity I've been searching for in the credit repair space, and I'm able to feel
confident helping other people. It's a true blessing.
Student, WhatsApp Community
“
The knowledge provided this past week is liquid gold. I feel like I won the lottery — I'm so proud to be a
"Kaironeekion."
Student, WhatsApp Community
“
My brain was too active to rest — I fell asleep watching the dispute videos and picked right back up the
next morning reading "Exposing the Collections Game." It's definitely an obsession that consumes
you.
Student, WhatsApp Community
“
A lot of people don't know where to find the right education and the person they can trust to teach them —
not scam them out of money. This is why I try to tell as many people as I can about the University.
Student, WhatsApp Community
Case Results
Proof, not promises.
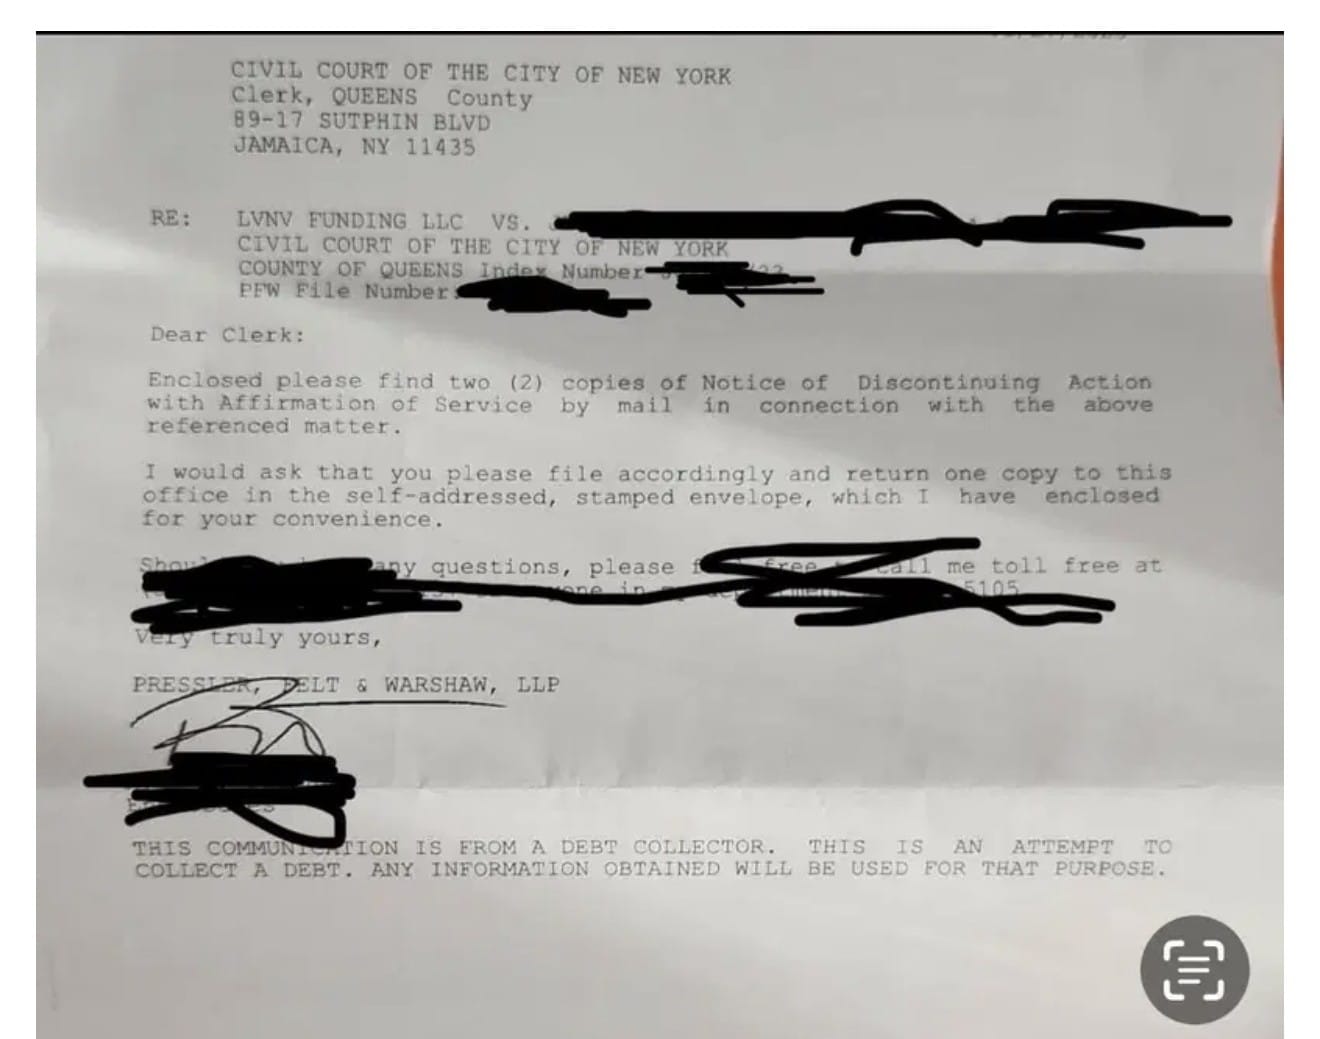
Pro Se Win · Civil Court, Queens County
Student's pro se victory against a billion-dollar company and its high-powered legal team.
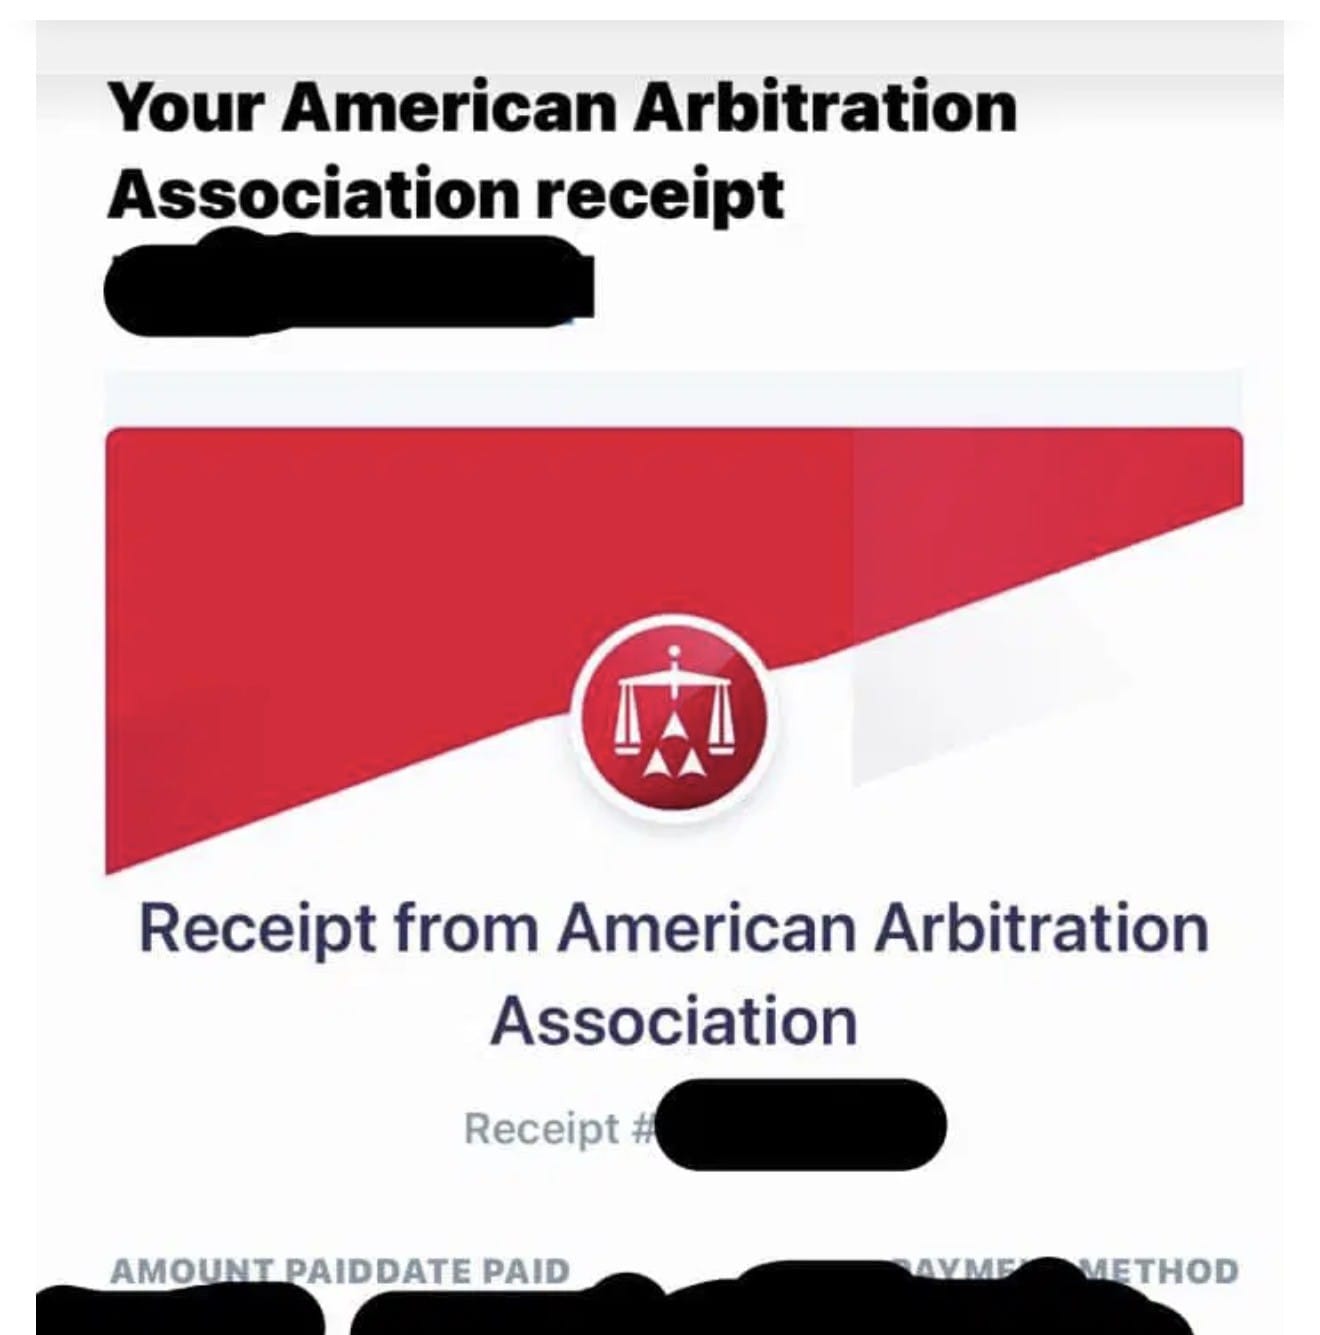
Arbitration Filed
Taking creditors to arbitration when necessary to get remedy.
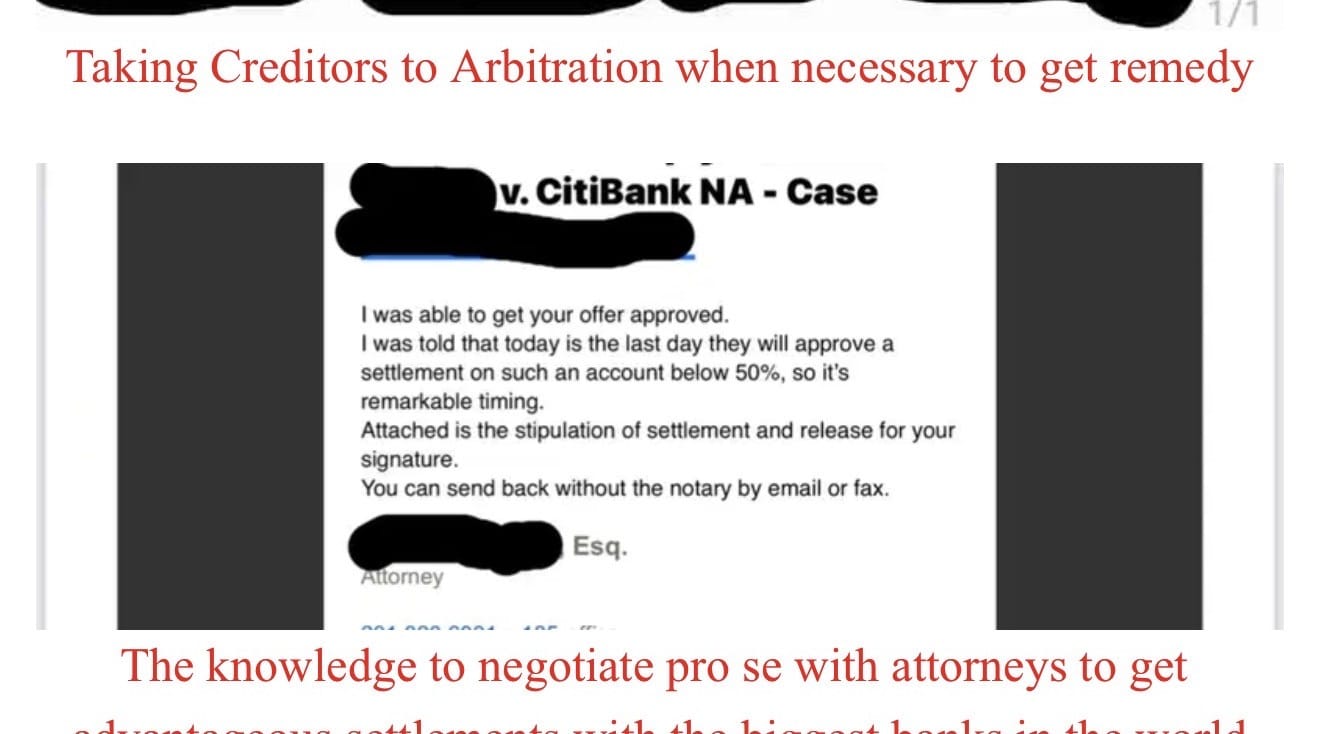
Settlement · CitiBank NA
The knowledge to negotiate pro se with attorneys to get advantageous settlements with the biggest banks
in the world.
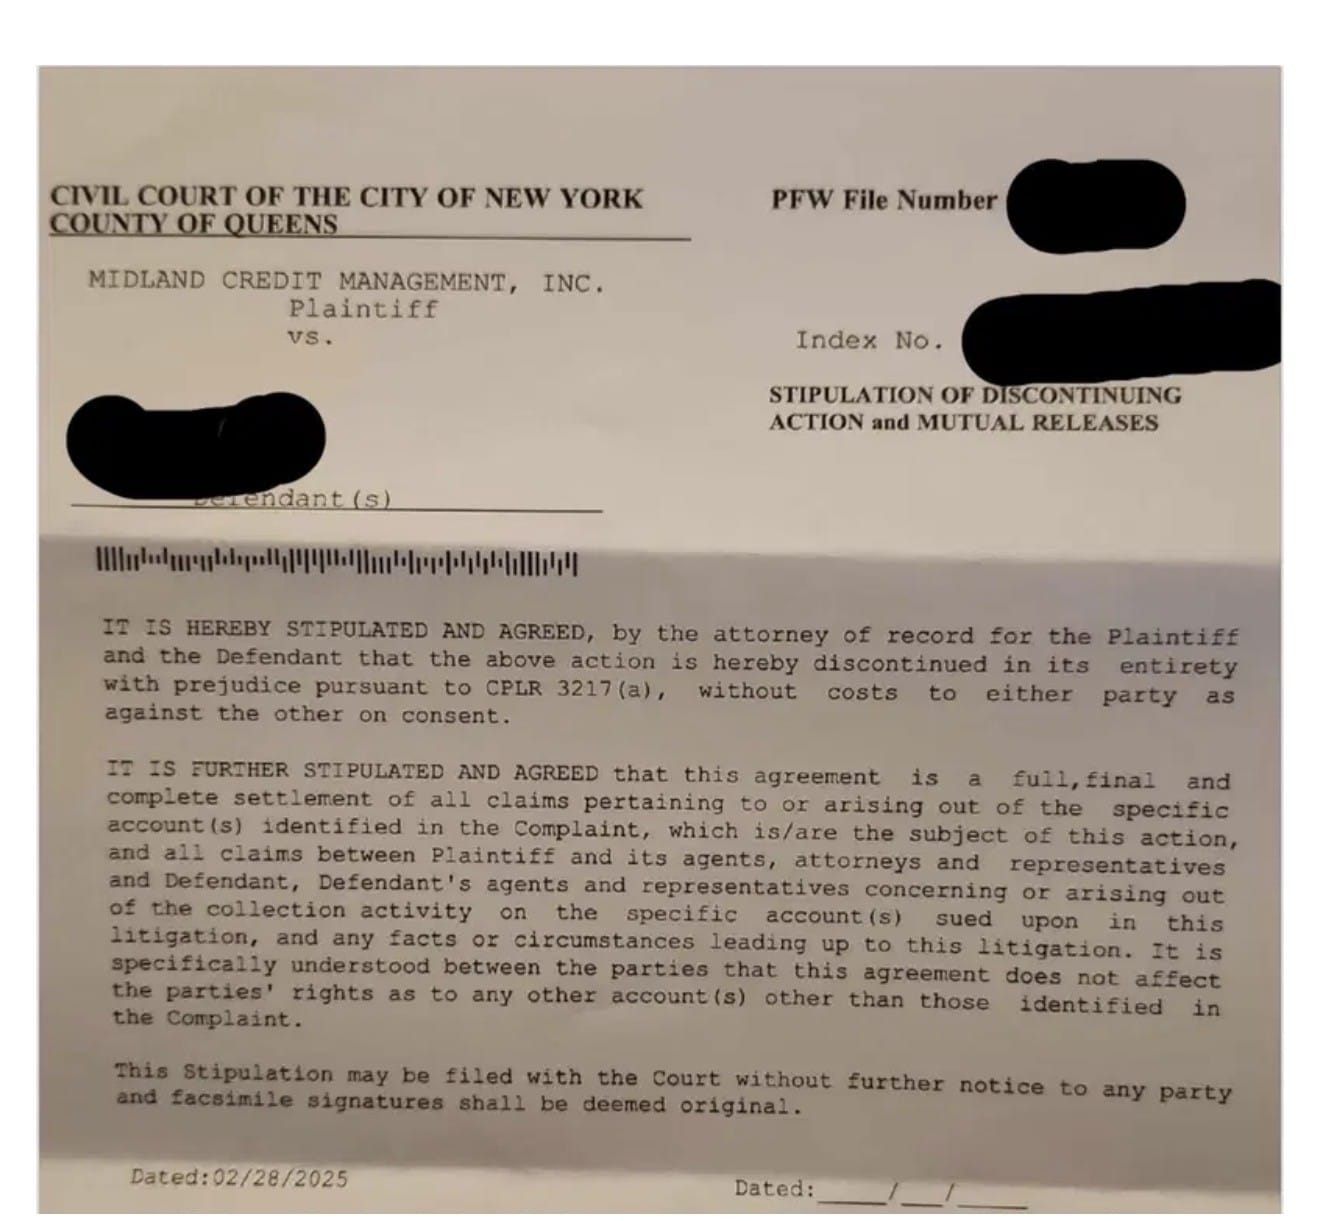
Pro Se Win · Midland Credit Management
Full stipulation of discontinuance and mutual release — the account, closed for good.
Names, index numbers, and other identifying details have been redacted to protect
student privacy.
Certifications
What you'll walk away certified in.
✓
FCRA Certification — master the laws governing credit reporting and consumer rights.
✓
FDCPA Certification — learn how to identify and challenge unfair debt collection
practices.
Ready to become a Kaironeekion?
Join the students already learning the law well enough to defend themselves — and their clients.
Everything you need to know before you enroll. Can't find your answer here? Reach out directly.
Enrollment & Cost
Enrollment is a one-time tuition cost. After your first month, a $79/month subscription keeps your access
active — live classes, mentorship, and the community.
Full tuition is $2,579 paid in full, or $2,974 across one of the four installment plans, plus the ongoing
$79/month subscription. See the Financing page for the full breakdown of all five options.
Five flexible options: pay in full, or put down 20%, 25%, 30%, or 50%, with the remaining balance split
across 4 or 5 monthly payments. No credit check required for any plan.
You can cancel your monthly subscription at any time from your student account. Your enrollment agreement
covers the specifics of tuition payments already made — check your signed contract, or reach out to us
directly with questions before you enroll.
Program Structure
Two kinds of students: credit repair business owners — especially those just starting out or stuck — and
consumers who want to understand and use their own rights under the law.
No. The program is built for laypeople. You're guided from the fundamentals through advanced application,
step by step, with live instruction and mentorship the whole way.
Live class is every Monday evening at 8 PM, running 2–3 hours. A separate 1:1 mentorship hour is available
on top of that for working through your own disputes.
Live sessions are educational instruction in consumer law — not individualized legal advice or
representation. Kaironeek University is a layman's education program; Richard Barrett is not a practicing
attorney.
Curriculum
No — while FCRA and FDCPA certification are core to the program, you'll also study TILA, ECOA, FCBA, the
E-Sign Act, foundations of contract law, and tort law as it relates to credit. See the full Curriculum page
for all 16 subjects.
You'll read and study the actual statutes, regulations, and case law directly — not just watch summary
videos. Live class each week reinforces and applies what you've studied.
Sixteen core subjects spanning the history of credit reporting, FCRA and FDCPA certification, TILA, ECOA,
FCBA, contract and tort law fundamentals, credit repair disputing, debt collection defense and litigation,
and arbitration. Full list on the Curriculum page.
Using What You Learn
Yes — the curriculum is built with credit repair business owners specifically in mind, so you can run a
compliant business and deliver results your clients can actually see.
Still have questions?
Send us a message and we'll get back to you directly.